LandOffer
Job search
W-2 Contract vs. 1099 Tech Work: Questions to Resolve Before Applying
Resolve the proposed employer, work control, payment timing and benefit terms before pursuing US W-2 contract or independent contracting opportunities.
Before applying to a US W-2 contract or “1099” tech listing, identify the proposed employer or customer, actual working arrangements, payment terms and benefit responsibilities. A contract assignment can involve employee status; a higher advertised contractor rate does not establish higher take-home income. Use the label to identify what arrangement is proposed, then examine its terms. Choosing a preferred tax form does not settle worker classification.
LandOffer publishes this guide and offers a place to browse recent roles. We checked the official sources on October 12, 2026, without assessing an individual's legal or tax situation. Amara, Juniper and Maple below are fictional; their documents and replies are invented teaching examples. This guide helps organize an application decision and a useful professional consultation.
Separate the assignment period from the proposed relationship
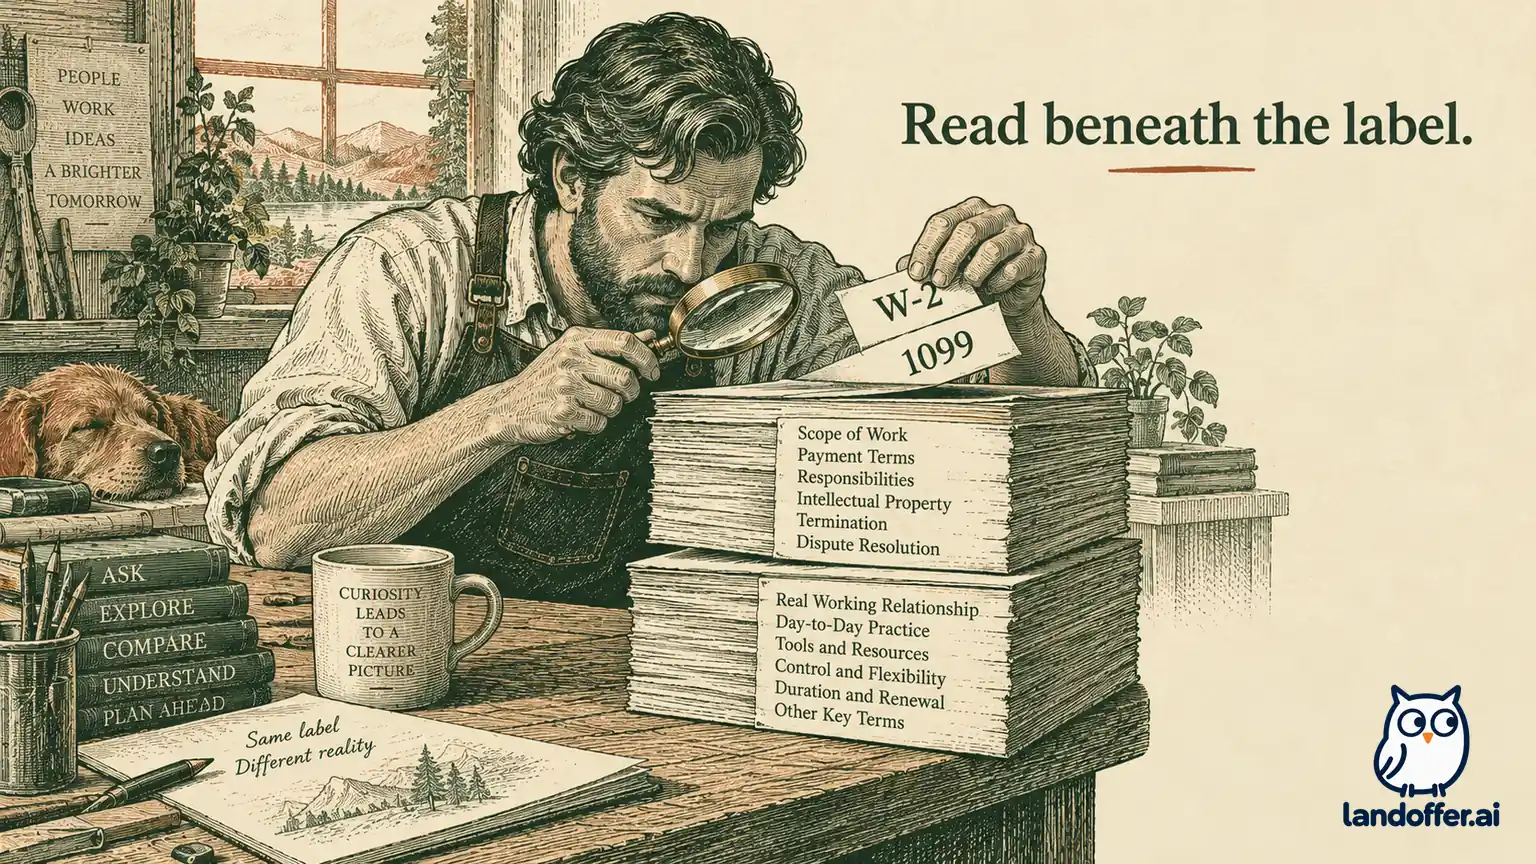
“Contract” can describe a limited assignment, an agreement to supply services or a recruiter's job category. Those meanings do not all establish independent contracting. A W-2 contract advertisement generally proposes employment with wages reported as employee compensation, potentially through a staffing firm serving a client. Identify the employing entity rather than assuming the client would employ you.
An advertisement using “1099” generally proposes an independent-contractor relationship. Ask who would contract with you and pay invoices, what services are being purchased and which written terms apply. The terminology alone does not establish that the proposed classification is correct.
Keep duration, hours and relationship in separate fields. “Six months,” “full time,” “hourly” and “remote” each answer a different question. None supplies the missing employer identity or all the facts about independence. A remote backend assignment still needs an explanation of who directs the work.
This distinction changes the search. If you want employee employment, a staffing-company W-2 opportunity may belong in your review queue. If you want to operate an independent services business, a project description needs enough detail to evaluate that business engagement. Neither preference authorizes a company to classify a relationship incorrectly.
Avoid treating incorporation, a laptop or a signed document as a shortcut around the rest of the inquiry. Gather the operating facts before drawing conclusions. Ask the recruiter for missing operating facts, review the actual terms and take classification questions to someone qualified to assess the applicable rules.
Use official guidance for the question it actually answers
The IRS classification overview groups evidence into behavioral control, financial control and the type of relationship. It considers the whole relationship rather than a fixed score or one decisive factor. It also describes general withholding differences between employee wages and independent-contractor payments.
Use those categories to gather facts: who sets methods and schedules, controls business expenses and supplies tools, and what continuing relationship is intended. These are information prompts, not a self-administered legal test. The IRS also provides Form SS-8 for an official employment-tax determination; it is not an instant pre-application answer.
Federal labor guidance concerns another question. On our review date, the Department of Labor's 2026 rulemaking page described a February 26 proposal to replace its 2024 analysis and said that analysis was no longer being applied in investigations. The page we read still described a proposal; that observation does not independently certify every rule or court decision applicable to a particular engagement. An agency enforcement approach and the rules relevant to an individual dispute should not be treated as interchangeable.
The proposal's FAQ expressly distinguishes other federal, state and local classification standards. It also explains that an employee cannot waive FLSA-protected rights by choosing independent-contractor status. A recruiter's agreement to your preferred label therefore does not settle those obligations.
For a state example, California's official FAQ describes an ABC test and exceptions or alternative standards. Do not turn that into a rule for every state, or assume a software-engineer title automatically establishes a licensed-professional exception. Ask which jurisdictions and facts apply to the proposed work.
The useful conclusion is narrower than declaring a role legal or illegal: save the actual location, parties, duties and control arrangements so qualified advice can address the right situation. Recheck dated guidance when you reach an agreement. This article does not certify the legal status of a posting from the wording on its card.
Compare two completed terms records
Fictional teaching case: Amara seeks backend work and is willing to consider a 20-week employee assignment. Before investing in an application, she needs a named payer, a workable payment schedule and enough information to evaluate health coverage. She is open to investigating independent project work, but has not decided to accept its business responsibilities.
Juniper J20 and Maple M12 both advertise remote API work. Their initial documents provide the following invented information:
| Field | Juniper J20: advertised W-2 assignment | Maple M12: advertised 1099 project |
|---|---|---|
| Parties | Juniper Staffing named as proposed employer; client disclosed | Maple named as customer; contracting document requested |
| Work period | Expected 20-week assignment | Proposed 12-week project |
| Work organization | Client lead assigns daily tickets; agency handles employment administration | Deliverable described, but schedule and method requirements missing |
| Payment | Hourly employee pay; payroll dates not supplied | Invoices payable 30 days after acceptance; acceptance criteria missing |
| Benefits | Agency says coverage available; eligibility, cost and start date missing | No employee benefits promised; required insurance and expenses unresolved |
| Initial decision | Request payroll and coverage information | Request operating and payment terms before evaluating further |
Neither row is an offer Amara has accepted. Juniper's duration is an expectation, while Maple's project period does not establish when every invoice will be accepted or paid. The documents have different gaps, so sending the same generic question to both would waste the opportunity to clarify them.
For Juniper, Amara can name the organization expected to employ her and the person assigning technical work. She cannot yet decide whether the coverage timing meets her needs. “Available” is insufficient because an enrollment opportunity and effective coverage are different facts.
For Maple, the immediate uncertainty includes the proposed operating model. A deliverable title does not explain whether the customer will dictate a daily schedule, require exclusivity or direct the methods. Amara records these as missing facts without declaring the project properly or improperly classified.
Her completed comparison produces two targeted inquiries before she spends time on either assessment. She keeps both records pending because the requested answers could change her application priority.
Resolve payment mechanics before comparing money
For employee arrangements, request the rate unit, expected paid hours, payroll schedule and treatment of leave or assignment interruptions. Ask where the applicable benefits and overtime terms are documented. Do not infer that all hours mentioned in a posting are guaranteed or that every W-2 assignment supplies the same package.
For proposed independent work, request the billing unit, invoice process, acceptance conditions, payment deadline and expense responsibilities. Identify who can approve additional work and how changes to scope are documented. A rate is hard to evaluate when the customer can request work beyond the original deliverable without a clear change process.
The IRS self-employed tax center describes general income-tax and self-employment-tax obligations and estimated-tax procedures. Use qualified tax advice for your own amounts and filing obligations. A job-search comparison should not substitute a universal percentage or hourly multiplier for those facts.
In Amara's fictional Maple record, “30 days after acceptance” starts a clock only after an event whose definition is missing. She asks which acceptance criteria apply, who reviews the delivery, when that review must finish and how disputed deliverables are handled. The advertised rate leaves that timing uncertainty unresolved, even when the number is attractive.
She also keeps business costs separate from personal take-home income. Equipment, insurance, administrative time and unpaid gaps need actual terms and appropriate advice. She does not assume every expense is deductible or every hour between projects can be billed.
This is enough to change application priority without calculating net income. An opportunity with unresolved payment triggers may warrant clarification before a long assessment, even if its advertised rate looks attractive.
Ask for a specific answer and preserve what it settles
Amara's unsent fictional inquiry to Juniper reads:
For J20, I understand Juniper Staffing would be my employer and the disclosed client would assign the backend work. Before I prioritize an application, please provide the payroll schedule, expected paid hours and applicable leave terms. Could you also point me to the coverage eligibility requirements, employee cost and earliest effective date for this assignment?
In a hypothetical reply, Juniper supplies weekly payroll dates and a benefits document naming an effective date that meets Amara's stated timing need. She records those supplied details and moves J20 to application review. That resolves her information gap; it does not guarantee employment, continued coverage or the assignment's full advertised duration.
If the reply repeats only “full benefits,” the gap remains. Amara can identify the unanswered item rather than restart the entire conversation. If the documented effective date is too late for her needs, she can deprioritize the role without asserting that Juniper's package is universally poor.
Her unsent fictional Maple inquiry asks for the contracting party, work-control expectations, acceptance criteria, invoice approval process and required insurance. In the hypothetical response, Maple defines the deliverable review period but still requires a fixed daily schedule and leaves exclusivity unclear.
Amara updates the payment field and keeps the operating questions open. She does not turn one improved clause into approval of the entire engagement. She holds substantial application work until the missing facts can be reviewed.
Build a useful packet for professional confirmation
Amara's completed fictional review packet separates facts from conclusions. It preserves the original posting and draft agreement, identifies her actual work location and lists the questions below.
| Issue | Fact or gap in Maple M12 | Appropriate next step |
|---|---|---|
| Control | Fixed daily schedule stated; authority over methods unclear | Obtain a concrete account of expected practice; seek classification advice |
| Other work | Exclusivity unanswered | Request the relevant clause and operating expectation |
| Payment | Acceptance review period now defined; dispute process unclear | Request written process; obtain contract advice if material |
| Costs | Insurance requirement not yet supplied | Ask for the requirement before obtaining an actual quote |
| Tax administration | Proposed independent payments; personal obligations unassessed | Review the actual arrangement with a qualified tax professional |
| Work authorization, if relevant | No personal determination made | Consult the appropriate qualified adviser using the specific engagement facts |
The recruiter or customer can explain proposed business terms. Payroll can explain its schedule, and a benefit administrator can explain the plan. Those contacts do not replace qualified advice about legal classification, contract consequences or an individual's tax situation.
Keep the packet focused. Private identifiers, full tax returns and unrelated employment documents do not belong in a routine first recruiter inquiry. Provide necessary sensitive information only through an appropriate verified process when there is a reason to do so.
The completed decision is to pursue J20 after ordinary role checks and keep M12 pending. If later advice or documents change a material fact, Amara revisits the decision rather than defending the first label she saved.
Choose one listing from your notes or LandOffer's recent roles. Record the proposed parties, work organization and payment terms, then name the one unanswered question that changes whether you apply. Your existing notes are sufficient. Choose recruiter clarification, document review or qualified advice for that question, and keep the role pending until the answer supports your next action.