LandOffer
Pay & Benefits
Reading Your Retirement Plan's Fee Disclosure: Find What Is Charged and Who Can Explain It
A fully annotated fictional 401(k) disclosure separates recordkeeping, optional service charges and investment expenses. A statement cross-check and complete administrator inquiry resolve the direct administrative label while keeping an unexplained charge and embedded-cost question open.
Read a retirement plan's fee disclosure alongside its current investment information and your account statement. Separate plan administration, charges for particular services, and investment expenses. For each item, write down its amount or rate, whether it is a direct charge or investment expense, the period it covers and the contact responsible for explaining it. A statement showing one fee does not establish the total cost, and a listed service fee is not proof that you incurred it.
This LandOffer.ai guide focuses on understanding documents for a US workplace 401(k), using official Department of Labor, eCFR and SEC investor information. Its plan, participant, disclosure excerpts and correspondence are entirely fictional. Only the simple fee arithmetic was actually executed locally. No account was accessed, investment selected, fee challenged with an employer, transaction performed or personalized financial recommendation made.
Identify the plan and the documents you are comparing
Start with the plan's full name, the disclosure date, the period covered by the statement and the designated contact. Confirm that the investment's name and share class match the actual plan option. Use the exact option and share class in the plan; a similarly named retail fund or an outdated document may have different expenses. Retain the document version instead of copying a percentage into an undated note.
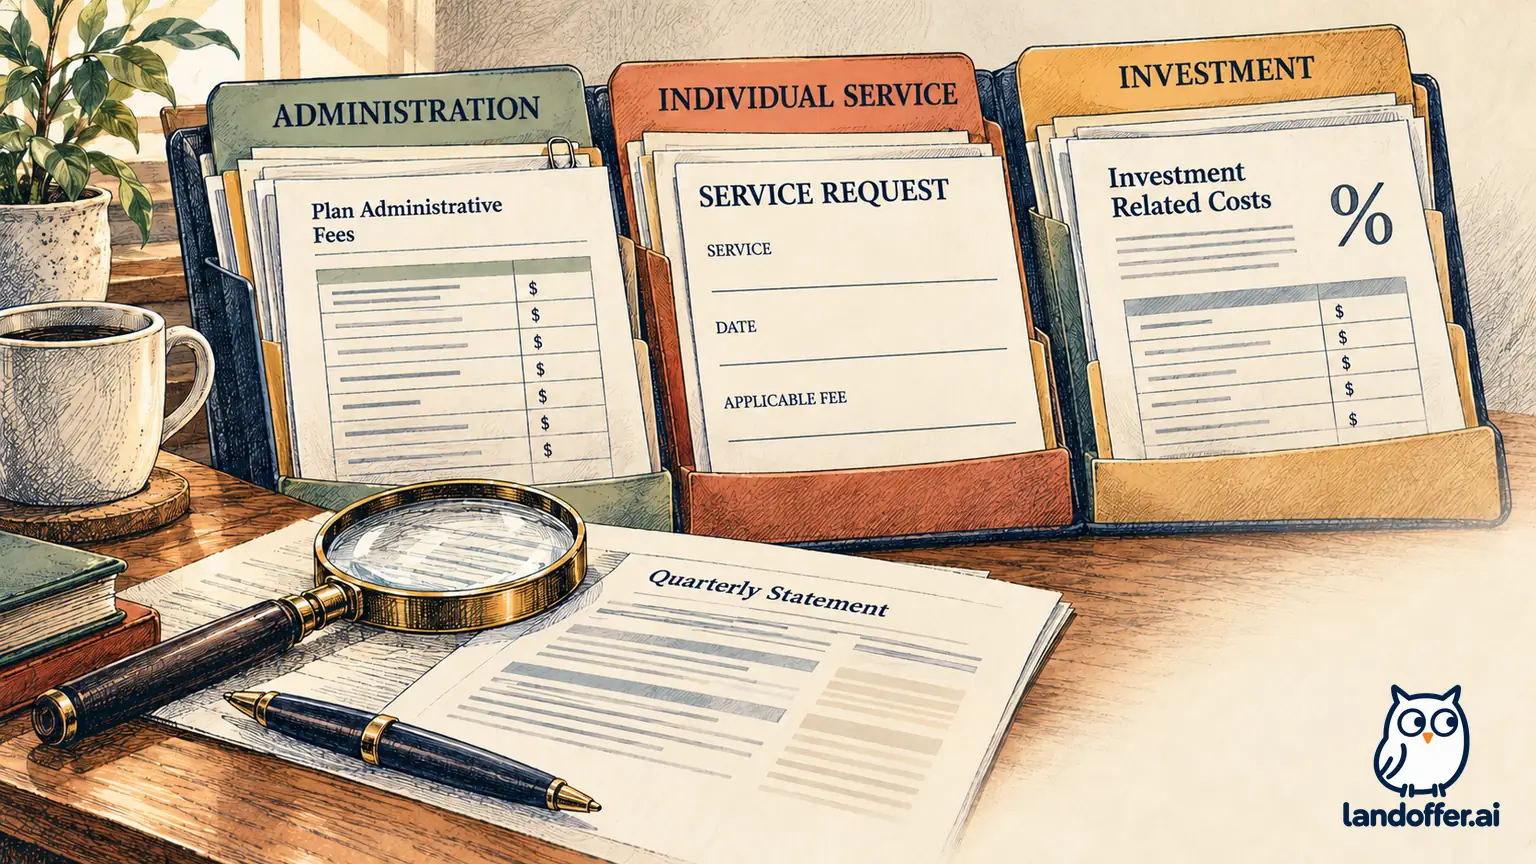
The Department of Labor's A Look at 401(k) Plan Fees distinguishes administration, investment and individual service fees. It explains that administrative costs may be paid in different ways, including direct account charges or through investment arrangements. Its explanation is a starting point for locating costs, not a determination that your employer charges a particular amount.
For covered ERISA participant-directed individual account plans, 29 CFR 2550.404a-5 addresses plan-related and investment-related disclosures. Among its provisions are annual information about certain fees and charging bases, and at least quarterly statements of specified administrative and individual charges actually taken from the participant account. Its coverage is not every arrangement called a retirement plan; ask the administrator which documents apply to yours.
An annual fee description and a quarterly statement serve different purposes. One explains what may be charged and how; the other can identify particular charges taken during a period. A current investment comparison chart or prospectus adds information that a statement's transaction list may not display as a separate debit.
Completed disclosure annotation: three kinds of cost
In this fictional case, Theo participates in the Fernbank Systems 401(k) Plan. He reviews its January 2, 2026 fee disclosure, the listed investment information current on September 30, and his July–September statement. He wants to understand charges, not decide whether to move money or select another investment.
The invented disclosure uses the following terms. These rates and service arrangements belong only to the example; they are not typical prices or a claim about an actual plan or fund.
| Document excerpt | Theo's annotation | What still needs confirmation |
|---|---|---|
| “Participant recordkeeping: $48 annually, assessed as $12 each quarter to the participant account.” | Plan administration; a flat direct account charge under these fictional terms, rather than a percentage of balance. | Check the statement's code and whether any updated notice changed the amount or allocation. |
| “Loan application processing: $75 per processed application.” | Individual service fee triggered by the stated service. Merely appearing on the schedule does not mean Theo paid it. | Theo reports no loan application; this item does not explain an unrelated $25 debit without further evidence. |
| “Fernbank Example Investment, Class P: total annual operating expenses 0.35%; $3.50 per $1,000.” | Investment-level annual expense information for the exact fictional option and class. It is not a separate quarterly recordkeeping charge. | Identify the current document and any conditions or updates; do not substitute another share class. |
| “Other plan administrative expenses may be paid through investment arrangements; consult the plan administrator for applicable details.” | The direct $12 fee alone may not describe every administrative cost borne through the plan's arrangements. | Ask which costs are already reflected in the investment expenses and which, if any, are additional to the account charges. |
Use the category to locate the explanation, then look for evidence that the charge actually applied to the account. Theo has identified the disclosed $75 service price but has not established that the service occurred. Likewise, the 0.35% investment expense information identifies a charging basis, not a new cash withdrawal from the statement.
The SEC's mutual fund explanation explains that funds pass costs to investors through fees and expenses deducted from net asset value. For a mutual fund, that helps explain why ongoing investment costs may not appear like a separate account transaction. Other investment structures can work differently; identify the product actually offered by the plan.
Read percentages and dollar illustrations without inventing a charge
An expense ratio of 0.35% is 0.0035 as a decimal fraction. Multiplying by $1,000 gives $3.50 for a simplified annual illustration. Under the covered rule, specified investment expense information includes annual operating expenses as a percentage and a dollar illustration per $1,000 under stated assumptions.
For a separate teaching calculation, $10,000 held constant for a full year at an unchanged 0.35% would correspond to $35 in annual expense arithmetic, assuming no returns, contributions or withdrawals. This is not Theo's balance history or a reconstruction of his actual investment cost. His balance could vary, and an actual product's calculations and terms require its own information.
Do not turn that annual $35 illustration into a quarterly statement debit, divide it into an asserted amount paid each quarter, or add it again to a return figure that already reflects those expenses. It belongs in a clearly labeled explanation of scale, not the column for confirmed account transactions.
Also check what a quoted percentage includes. The SEC’s July 2025 fee-table bulletin describes annual operating expenses, shareholder fees, share classes and fee waivers or reimbursements. A document may distinguish gross and net figures or show conditions affecting which rate applies. Ask which figure applies and for what dates. Do not assume a lower displayed rate is permanent or that two component percentages should be added on top of a total that already includes them.
The local Decimal calculation completed nine checks of these fictional amounts and distinctions: four $12 quarterly charges equal $48, the percentage conversion gives $3.50 per $1,000, and the constant-$10,000 annual illustration is $35. The nine checks confirm the written amount calculations and mismatched service prices. They do not validate a real statement, establish legal compliance or judge whether a fee is reasonable.
Cross-check the quarterly statement against the disclosure
Theo's fictional statement shows two fee debits: ADMIN −$12.00 on September 30 and SVC −$25.00 on August 14. It has no separate transaction labeled “0.35% investment expense.” Theo records the charges without assuming that the missing investment debit means no investment expenses were incurred.
| Statement item or question | Cross-check result | Classification and next step |
|---|---|---|
| September 30 ADMIN, $12 debit | Amount matches the disclosed quarterly recordkeeping amount. | Provisional administration match; obtain the provider's code explanation and current allocation basis. |
| August 14 SVC, $25 debit | Does not match the disclosed $75 loan-processing price. Theo reports no loan or distribution request. | Unexplained direct charge; request the service, triggering instruction, authority and applicable fee schedule. Do not label it fraud or a confirmed error. |
| Investment expense information, 0.35% annually | No separate debit to match in the transaction list. | Keep the investment document separate; ask how expenses are reflected and what is already included. |
| Visible fee-debit total | $12 + $25 = $37 during this statement period. | Total of the two visible debits only, not the full cost of the plan or the investment. |
Keeping those findings separate prevents an unfamiliar code from being assigned to the wrong service and an annual illustration from being added to quarterly debits. Theo does not equate the $25 entry with the nearest familiar service just because both are fees. He also does not calculate $37 plus $35 and call $72 the quarter's total cost: the $35 is a full-year simplified investment illustration, not a confirmed quarterly charge.
Theo keeps the original statement and a working copy with annotations. He records the statement page, transaction date, code and amount, without placing full account numbers, Social Security numbers or login details in an ordinary email. He will use the plan's verified secure contact route if identifying account information is necessary.
Send a complete question to the responsible contact
The disclosure names plan administrator Lila as the contact, with the recordkeeper handling transaction-code details. Theo prepares this fictional October 12 inquiry through the plan's designated secure channel:
I am comparing the January 2 fee disclosure with my July–September statement. Please confirm that these are the current documents for my participant account, and identify any applicable updates.
The September 30 ADMIN charge is $12. Please confirm whether this is the disclosed quarterly participant recordkeeping fee and whether any additional administrative expenses are paid through the investment arrangements. Please identify where those expenses are described so I do not count them twice.
The August 14 SVC charge is $25. I do not recognize the service, and I have not requested a loan or distribution. Please identify the service, the instruction or event that triggered it, the applicable fee schedule and the party responsible for reviewing a disputed charge. The $75 loan-processing entry on the disclosure does not explain this amount by itself.
The investment chart lists Class P annual operating expenses of 0.35%, with $3.50 per $1,000. Please confirm the current document and explain how those expenses are reflected, including anything already included in reported investment returns. I am requesting clarification, not instructing an investment change or authorizing a new service.
The message includes answerable document and transaction questions. It does not ask the contact to guarantee a return, recommend a security or declare every fee reasonable. In a real inquiry, distinguish the legal plan administrator from a recordkeeper, a payroll contact or an investment provider; they may have different responsibilities and information.
Record the answer without closing unresolved items
Lila's fictional October 14 response confirms that the $12 debit is the current quarterly recordkeeping fee. She explains that the Class P operating expense figure is investment-level information rather than a separate debit and directs Theo to the current investment document. She has asked the recordkeeper to investigate the $25 code; she does not yet identify its service or authorize a reversal.
Theo's October 15 readback marks the $12 explanation confirmed within the case, the investment document identified, and the $25 charge still open. He separately asks Lila which administrative costs, if any, are reflected through the investment arrangement; that question has not been answered. Acknowledgment of an inquiry is not a finding that the charge was correct or a promise to refund it.
He retains the inquiry reference and the stated next contact, without inventing a resolution deadline. If the explanation remains missing or inconsistent, he can ask the plan administrator about the applicable review process and consult official EBSA assistance information. This article makes no determination that his hypothetical plan violated a disclosure rule, and no real complaint was filed.
Further workplace guides are available from LandOffer.ai. Finish the review with a map of what is disclosed, what was actually debited, what is reflected through investment expenses and what remains unexplained. Record the administrator’s actual answer and leave unresolved charges open; do not treat an acknowledgment as a refund or investment instruction.
Sources and Further Reading
US Department of Labor: A Look at 401(k) Plan Fees — administration, investment and individual service fees and charging arrangements; checked October 28, 2026.
eCFR: 29 CFR 2550.404a-5 — covered-plan disclosure requirements, including paragraphs (c)(2)–(3) and (d)(1)(iv); title current through October 26, 2026 when checked.
SEC Investor.gov: Mutual Funds — fees reflected through net asset value and product-document context; no actual fund or participant account reviewed.
SEC Investor.gov: Mutual Fund and ETF Fees and Expenses — July 23, 2025 staff educational bulletin on fee tables, share classes and waivers; not a new legal rule.